Thursday, February 4, 2016

View the Second Set of Marquette AIM Student Equity Pitches for the 2016 Spring Semester on Friday, February 5th at 3:00 CST


You Can Join the AIM Program Student Equity Presentations on Friday, February 5 at 3:00 pm CST  

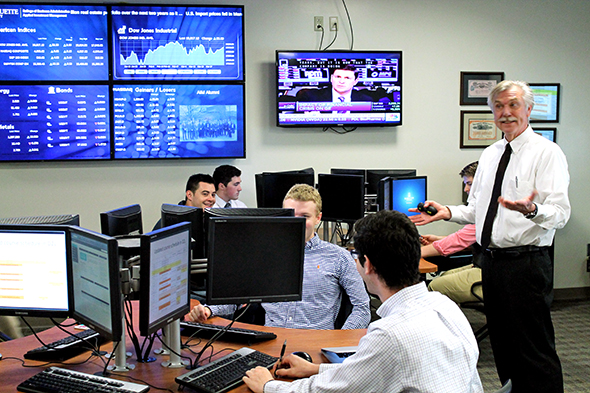
The AIM student equity pitches take place each Friday afternoon during the semester – either in the AIM Room or at a local investment company. The students prepare and distribute a professional equity write-up (note: every AIM write-up since the inception of the program in 2005 is archived here). 


This week’s equity write-ups can be found at:


The students are responsible for making a five-minute pitch before their peers, faculty and any alumni or investment professional in attendance (note: the Friday afternoon equity presentations are also webcast live - see below on how to join the webcast).

Following the student’s pitch the floor is opened for questions and answers for about ten minutes. This has been highly instructive as the students must be prepared to defend their investment recommendation and answer questions in an extemporaneous manner.


How to view the AIM Student Equity Presentations on February 5, 2016:


How to comment using Twitter:

 
https://pbs.twimg.com/profile_images/692077587577839616/pqpZVVD0.png
Go to the MarquetteAIM Twitter account (you can use Search Twitter on your site) and click Follow
During AIM presentations, go to #AIMpitch and follow the tweets (discussion) on Twitter (it will also be appearing on the Rise Display Board in the AIM Room and on your smartphone)

Click here to go to AIM Twitter

    Tweet your comments and questions during the AIM equity pitches and remember to:


    • Follow the rules of etiquette for using Twitter during AIM pitches
    • Use the hashtag #AIMpitch to start each tweet
    • Use $TICKER (note: this is called a cashtag and it be should the unique ticker/symbol for the stock that is being presented, ex: $TSLA)
    • Keep you comment short because each tweet is limited to a maximum of 140 characters
    • Example for Tweeting on a student’s Tesla equity pitch (note: the ticker for Tesla is TSLA):
      •  #AIMpitch $TSLA How do lower gas prices impact demand for electric cars?


32nd AIM equity update by John Grant, Mobileye (MBLY): Tough Short Run, But Exciting in the Long-Term

Mobileye N.V. (MBLY, $28.70): A More Modest Take on Future Alpha
By: John Grant, AIM Student at Marquette University

Image result for mobileye logo

Disclosure: The AIM International Equity Fund currently holds this position. This article was written by myself, and it expresses my own opinions. I am not receiving compensation for it and I have no business relationship with any company whose stock is mentioned in this article.

Summary
·         Mobileye N.V. (NYSE: MBLY) designs and develops software and related technologies for camera-based advanced drives assistance systems (ADAS) for major motor vehicle corporations in North American, European, Middle Eastern and Asian countries.

·         The stock has been on the decline since $61 peak in 7/2015, revenue guidance for 2016 fell below consensus (40% y/y growth, $335M)

·         Big announcement at CES, Road Experience Management (REM) solution minimizes costs, improve revenue guidance.

·         Auto suppliers are becoming increasingly cheap and have positive earnings outlook, FY16 launches appear attractive as MBLY adds to their backorder.

·         Legal momentum to speed up the integration of ADAS in Europe, Americas and Asian countries.

Key Points:
As MBLY’s stock price continues to slide (-36.95% 3-month change) institutional investors are taking advantage of the underpriced security. Of the six largest institutional holders, Fidelity Management & Research Co. was the only one to shed a portion of its position, the other five have exponentially increased their exposure to MBLY (Figure 3). MBLY continues to hold a leading position in the ADAS market as they expand their data collection, maintain a 100% RFQ success rate and legal tailwinds become more relevant.

In January 2016 MBLY made a presentation at CES introducing their Road Experience Management (REM). The system uses advanced artificial intelligence to create maps based on local coordinate systems, the program requires a very low bandwidth. This low bandwidth and ease of integration to their other systems makes MBLY’s REM the best product when observing cost and performance.

MBLY has already begun efforts with General Motors to integrate REM into existing program launches, the relationship with GM has been growing significantly. On January 5th, 2016, MBLY announced they had signed a Memorandum of Understanding with Volkswagen and further announced a strategic partnership to implement the REM into VW’s vehicles. MBLY has identified a third OEM customer, of comparable size to GM and VW, will be announced in 2016. By announcing REM and the partnerships already established, MBLY is further increasing barriers to entry for competitors.

MBLY continues to win every RFQ which it participates in, adding VW as a customer will be a catalyst for future ADAS integration and revenue growth. Management indicated the firm has added a high volume of new launches for the back end of FY16, including five programs and 52 vehicles. The Detroit Auto Show gives investors’ confidence there will be a higher volume of new vehicle launches in 2016, an opportunity for organic revenue to increase in 2016.

Legal tailwinds remain favorable as government bodies in Europe (30.2% of total revenues), Americas (55%) and Asia (5.8%) continue to require ADAS and other safety technologies in vehicles. Driver error accounts for 80% of all fatal car accidents, which are expected to be the fifth leading cause of death by 2030. ADAS technologies have been proven to reduce collisions. OEM’s will be required to have at least one ADAS in their vehicle to meet a 5-star rating by the end of 2016. Additionally, AEB’s (MBLY specialty) are going to receive a higher weighting in an overall score on safety ratings, making the MBLY product more in demand. NHTSA has ADAS’ on their list of recommended technologies and are continuing to make a push on adding it to the required list to meet a 5-star safety rating in the USA. Lastly, the China NCAP expects ADAS to become a criteria of their 5-star safety rating by 2018 year end.

Figure 1
Source: FactSet


What has the stock done recently?
MBLY has had a tough run recently with the 3 month stock price change at -36.95% versus -32.12% YTD (Figures 1 & 2). This largely is attributed to their downward revenue revisions and investor focus on near-term profitability. MBLY has a 52 week beta of 1.32 and it has become common to see 4-6% price fluctuations on a given day. Analysts have begun slashing unrealistic 12-month price targets, which has caused heighted negative perception towards the stock. However, increasing revenues, earnings and free cash flow have depressed price multiples from a historic perspective and make MBLY an attractive long-term investment at this time.

Figure 2
Source: FactSet

My Takeaway
I am still bullish on MBLY, however I would only recommend the stock to investors with a long term holding period. MBLY continues to reiterate the growing demand for ADAS products through their contract wins (100% success rate) and legal tailwinds in regions of major revenue exposure. MBLY’s dominant market share and unique business model as a third tier supplier will allow for them to dramatically increase production to realize meaningful revenues and earnings in the coming years. MBLY is attractively priced at $28.70 (2/1/16 close) with a P/E (NTM) 38.6x vs. 91.1 5-year average and a P/S of 32.8x vs. 66.9x 5-year average. I believe MBLY will remain fairly volatile until more reported product launches between the end of 2016 and 2018 begin to hit the market and the firm recognizes meaningful revenues and earnings.  


Figure 3
Source: FactSet

Wednesday, February 3, 2016

31st AIM equity update by Mark Lakowske, Calavo Growers (CVGW): A stock that's green and growing!

Calavo Growers, Inc. (CVGW $50.43)
Tableside Guac as a Promising Stock?

By: Mark Lakowske, AIM student at Marquette University

Image result for calavo growers logo 

Disclosure: The AIM Equity Fund currently holds this position. This article was written by myself, and it expresses my own opinions. I am not receiving compensation for it and I have no business relationship with any company whose stock is mentioned in this article.

Summary
• Calavo is leading the guacamole craze across the United States
• The company's profitability is on the rise
• This is a resilient stock during these past few volatile weeks
• There is a flood of new institutional investors in the stock

Calavo Growers, Inc. (CVGW) is one of those companies that most consumers have not heard of—unless you happen to be an avocado aficionado. Odds are favorable that you have had consumed a Calavo avocado whether you know it or not. Ever buy an avocado from Whole Foods? Ever order guacamole from Qdoba? Ever get guacamole on your burger at a Chili's? All of those stores and restaurants are Calavo’s customers. Calavo also sells salsas and other pre-packaged meals and salads along with its avocado business. I tend to focus more on their avocado business because that’s where the money is at for the company.

The demand for avocados has been consistently on the rise for the past four years. According to the Haas Avocado Board, 1.137 billion pounds of avocados shipped across the world from California, Mexico, Chile, The Dominican Republic, and New Zealand in 2011. In 2015, there were 2.181 billion pounds shipped—an impressive growth rate of 91.82% in only four years.

The consistent growth in avocado demand has fared well for Calavo’s profitability. Return on equity and return on assets has jumped from the low single digits to low teens in the most recent quarterly report. Calavo’s farmers have had to become more innovative in order to avoid adverse effects from the drought in California. They have improved their farming techniques so their trees do not require as much water to grow. This has led to better margins within the company—increasing roughly 10% in 2015.

What has the stock done lately?

To say the equity markets are off to a shaky start in 2016 is an understatement. Only two sectors in the S&P 500 are in the black YTD. Since the start of 2016, the S&P 500 is down 8%, the Dow is down 8.8%, and the Russell 2000 (where CVGW is listed) is down a whopping 12.19%. In the same time period, CVGW is up 3%! With some analysts worried about a possible recession in 2016, a stock in the black is going to be hard to come about. In 2015, Calavo’s stock appreciated 22%. CVGW’s stock vastly outperformed its peers in 2015. $FDP rose 14%, $CAG improved 6%, and $HAIN tumbled 38%.

Past Year Performance: 2015 was a stellar year for Calavo Growers. Sales were up 9.5% from 2014, net income ripped up from 0.10 in 2014 to 27.20 in 2015, and gross margins are currently above the historical five year average. As mentioned before, the stock appreciated 22% in 2015 and short interest remained in the low single digits.


Source: FactSet

My Takeaway
Although this recent market correction and increased volatility has some investors scared for the near future, Calavo Growers, Inc. is a great option for portfolio diversity. The company has worked out some kinks in management in the past year and institutional investors are starting to pour money into the company. 

Over the past six months, the top fifteen institutional shareholders have increased their position over 1 million shares. Lord, Abbett & Co. recently increased their stake in CVGW by 433,000 shares. If Calavo keeps on performing like they are now and demand remains as stable as it has in the past, I would expect the stock to grow another 15, and maybe, even 20% in 2016.


Tuesday, February 2, 2016

Daniel Einhorn of Capital Midwest Fund Visited Marquette's Alternative Investment Class Last Week

Daniel Einhorn, Venture Capitalist, Visited Dr. Krause’s Alternative Investment Class on Friday, January 29, 2016

Daniel Einhorn, General Partner of Capital Midwest Fund, visited Marquette's campus last Friday.  He has over ten years of venture capital experience, evaluating, screening, and investing in private technology companies based primarily in the Midwest.

The students in Dr. Krause’s Alternative Investment class on Friday, January 29th had the opportunity to hear about venture investing from Mr. Einhorn. This is the fifth year that he has visited students at Marquette and discussed private equity investing.  

Mr. Einhorn is on various board of directors including: LiquidCool Solutions, Rapid Diagnostek, Physician Software Systems, Always In Touch and PreEmptive Meds. He is a member of the Board of the Entrepreneur Center at Illinois Institute of Technology, and the Southern Methodist University Alumni. He is on the board of COA Youth & Family Centers and the Jewish Museum in Milwaukee. He is a member of the Midwest Health Investment Network. In 2012, he was named Man of the Year for the Milwaukee Chapter of the Leukemia and Lymphoma Society.  

Dan-Einhorn.jpg
Daniel Einhorn
Capital Midwest Fund is a venture capital firm that invests primarily in the areas of life science and information technology. The fund concentrates on investments where companies have excellent management and technology, are performing an important function, and will address significant markets. He said that they look for management with successful previous experience; markets that are established and growing; defensible IP positions; and sustainable competitive advantages.


Daniel and the other principals of the fund are professionals who have operated in the investment banking, investing, life science and technology industries for many years. They have significant experience in raising money for early-stage companies and sourcing deals. In addition, they have significant experience in assisting management teams prepare viable business plans, evaluate strategic partnerships, and craft lucrative exits.

Dr. Krause said, "It is a privilege to have Dan join us each year in the classroom. His experience adds to the curriculum and the students enjoy learning firsthand from investment professionals."

Monday, February 1, 2016

30th AIM equity update by Ryan Woo, LeMaitre Vascular (LMAT): Interesting Medical Device Company for 2016!


LeMaitre Vascular, Inc. (LMAT, $14.85): “Compelling Value Proposition is Circulating”

By: Ryan Woo, AIM Student at Marquette University

Image result for LeMaitre Vascular,
 Disclosure: The AIM Equity Fund currently holds this position. This article was written by myself, and it expresses my own opinions. I am not receiving compensation for it and I have no business relationship with any company whose stock is mentioned in this article.

Summary
• LeMaitre Vascular, Inc. (Nasdaq:LMAT) is a medical device company that specializes in the treatment of peripheral vascular disease through its disposable and implantable products, which include balloon catheters, carotid shunts, biologic patches, radiopaque marking tape and vascular grafts.
• LMAT was added to the Russell 2000 in June 2015, which has allowed the stock to garner greater attention in the past six months.
• The expansion of the sales force into new regions and strong demographic trends should continue to allow LeMaitre to reach its target of 10% sales growth and 20% operating profit growth.
• A debt-free balance sheet gives LMAT flexibility with respect to cash deployment, which can allow the company to continue its acquisition activity, buyback shares, and/or raise its dividend.
• Although the stock has tumbled since reaching an all-time high of $18.44 at the end of last year due to a broad market sell-off, there is still a large runway for growth, and it is conceivable that shares can rise back to the all-time high.

Key points: LeMaitre Vascular Inc. remains 'in-play'. On June 26, 2015, LMAT was added to the Russell 2000, which has led to the increased volume over the past six months. This should prove beneficial to LMAT stock as it allows institutional investors to add the company to their portfolios. In addition, passive investors and indexes have to have greater exposure to the stock.

Since the company was added to AIM Micro-Cap portfolio in late October, LMAT has taken part in four healthcare conferences hosted by respected equity research firms like Canaccord Genuity, Stifel, Brean Capital, and Three Part Advisors in the middle of November. In addition, LMAT held an investor day in early December, which emphasized its three part strategy: the focus on the vascular surgeon, the target of niche markets, and the growth of the company through sales force expansion, research and development introductions, and acquisitions.

In addition to company-specific initiatives, LMAT also has the benefit of working with a population that caters toward the growth of its devices. Peripheral vascular disease is most common amongst those over the age of 65. According to company data, the percentage of the US population over 65 years old is expected to be 336 million in 2020, but this is expected to grow to 392 million by 2040, a CAGR of 7.7% which LMAT should be able to outperform as it gains market share in its niche markets and expands its global reach.

What has the stock done lately?
LMAT has been caught in the recent market sell-off due to oil and China concerns. As a result, the shares are down 14% YTD. The share price is still at the high end of its 52 week high-low range of $18.44-7.36. The company is set to report earnings either late this month or early February, which is the next catalyst for the stock.

Past Year Performance: LMAT has increased 92.61% in value over the past year, but the stock is nonetheless on the bargain table: LMAT's market valuation implies a ~20% discount to its previous high in December 2015. Share buybacks and an accretive acquisition could push the shares even higher.

Source: FactSet

My Takeaway
LeMaitre Vascular is doing a lot of things correctly, and further execution is key from this point going forward. The debt-free balance sheet coupled with plenty of dry powder equals an opportunity for LMAT to target larger acquisitions, which is beneficial as long as the company does not overpay nor dilute margins. The expansion of the sales force into new regions should allow LMAT to expand on its 10% market share.


Source: FactSet