Tuesday, May 10, 2016

66th AIM Equity Update by Conor Connelly. Sberbank Russia OJSC (SBRCY). "Emerging Market Value in an Eastern Europe Banking Giant"


Sberbank Russia OJSC Sponsored ADR (SBRCY, $7.62): “Optimizing Efficiency Russian Style”

By: Conor Connelly, AIM student at Marquette University

 Image result for Sberbank Russia

Disclosure: The AIM International Equity Fund currently holds this position. This article was written by myself, and it expresses my own opinions. I am not receiving compensation for it and I have no business relationship with any company whose stock is mentioned in this article.

Summary

• Sberbank Russia OJSC Sponsored ADR (SBRCY) provides emerging market exposure to the financial sector of the AIM International Equity Fund at a time when the worst of Russia’s turmoil is likely behind them.

• Management is currently executing a plan to cut costs and optimize efficiency

• Domestic growth in Russia is forecasted to steadily increase from its 2014 and 2015 lows, propelling consumption and loan growth.

• At the CFA ENGAGE Symposium on April 14 in Chicago, investor Bill Miller mentioned Sberbank as a financial that he would currently buy.

Key points: 2014 and 2015 were two years marked with economic turmoil in Russia. Four macro-economic themes propelled the country into a recession: accumulated structural problems and decelerated economic growth, a radical drop in oil prices, geopolitical sanctions, and the depreciation of the ruble. Sberbank stalled with minimal profitability, poor asset quality, low loan growth, deleveraging, and a rise in nonperforming loans.

In the last six months, however, Sberbank has seen a rise in mortgage origination, a growing deposit base, and an extension of credit into corporate segments. Additionally, management has begun to execute their cost cutting plan in order to optimize efficiency. They plan to cut the number of bank branches by 10-20% and lower domestic headcount by 14% by 2018. Achieving these goals would reduce the cost to income ratio by over 5%, reaching their 40% goal. It would also boost return on equity from 14% to 19%. Sberbank has already seen some of the positive effects from this plan. Net interest margin improved from 2.6% at the beginning of 2015 to 5.1% at year-end.

Sberbank is a key supplier of financial resources for the Russian economy. The corporate loan portfolio has continued to grow over the last two years, even with recessionary growth. About a third of the company’s corporate loan portfolio is made up of foreign currency denominated loans.

What has the stock done lately?

Sberbank was added to the AIM International Equity Fund in early December of 2015. Since being added, the stock has returned 20.5%. It took a dip at the end of 2015, but has rallied strongly in the last four months.                                                                  

Past Year Performance: Sberbank has increased 28.8% in value over the last year. It has outperformed the Russell Global x US by 42.84% on a total relative return basis. We expect the stock to continue growing into 2016 as its profitability is just starting to improve.


Source: FactSet


My Takeaway

Sberbank Russia is just beginning its cost-cutting program that is expected to boost efficiency and profitability. Hearing Bill Miller speak highly of the stock at the CFA ENGAGE Symposium in April enforced our outlook on Sberbank. We believe that this is a holding that could add a high level of alpha to the portfolio over the next 3 years and is an attractive emerging market play.


Monday, May 9, 2016

Nine Students in the AIM Class of 2017 Pitched the Fifth Set of Stocks on May 6th


AIM Students Presented Final Semester Stock Recommendations for the AIM Equity Funds


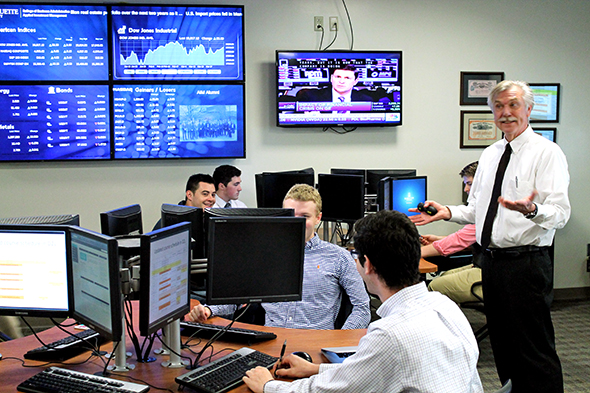
The fifth and final semester set of equity pitches were delivered by the Class of 2017 in the AIM Room on Friday. The nine AIM student presentations also were viewed on-line via a webcast by more than 20 alumni and family members across North America.

Nicholas Christman pitches PPERY
The opportunity for students to actively manage domestic and international equity portfolios has been an important part of Marquette AIM program’s experiential learning. The AIM students who presented on Friday included (Student Name, Company Name, Ticker, and Sector):
  • Taylor Smith  Atos (AEXAY)  International Technology
  • Brett Stuck  Shenandoah Telecommunications (SHEN)  Telecommunications 
  • Akash Vipani  AMN Healthcare Services, Inc. (AHS)  Consumer Discretionary
  • Michael Robinson  Trex Co., Inc. (TREX)  Industrials
  • Anthony DiSanto  China Mobile Limited ADR  (CHL)  International Telecommunications
  • Nicholas Christman  Bank Mandiri  (PPERY)  International Financial Services
  • Brian Fletcher  Omnicell, Inc.  (OMCL)  Technology
  • Dominic Delia  Vina Concha y Toro S.A. ADR  (VCO)  International Consumer Staples
  • Joe Mungenast  Merit Medical Systems  (MMSI)  Healthcare
Akash Vipani pitches AHS


Their AIM equity write-ups can be accessed at:


65th AIM Student Update by Mark Lakowske. Cracker Barrel Old Country Store (CBRL). "Will the fast casual concept take hold at Cracker Barrel?"


Cracker Barrel Old Country Store (CBRL $146.41)

Dumpling Platter with a Side of Expansion

By: Mark Lakowske, student at Marquette University


 Image result for crackerbarrel

 
Disclosure: The AIM Equity Fund currently holds this position. This article was written by myself, and it expresses my own opinions. I am not receiving compensation for it and I have no business relationship with any company whose stock is mentioned in this article.


Summary

  • Capitalizing Low Gas Prices
  • New ‘Fast Casual’ Restaurant Concept
  • Differentiated Business Model
  • Consistent as its Loyal Customer Base

Cracker Barrel Old Country Store (CBRL) might has historically been one of those sleeper stocks you come across now and again. Every quarter they hit or barely passes analyst estimates, little company expansion, but somehow manages to return 15% to their investors. Cracker Barrel had a tough time a few years ago when the price of oil was near $130 per barrel. As you have probably observed while driving to visit your relatives in Iowa, Cracker Barrel’s are only located near main interstates in rural portions of the country. Since the price of oil has come down significantly in the past year, there is little excuse to avoid that dreadful family reunion, so you might as well swing by a Cracker Barrel on the way for some old school southern style food.


Although it might shock the investment world, but Cracker Barrel might be on the brink of serious expansion. The company understands that their typical customer is starting to age quickly and they’ve got to start grabbing millennials to fill the void. The company announced plans for a new ‘fast casual’ concept restaurant set to launch in July 2016. Think Chipotle with biscuits and dumplings instead of burritos and rice bowls. Personally, this is pretty exciting news for me because I like how they are the first company to get into fast casual with a comfort food twist, and I would love to be able to grab some fried chicken and gravy in under ten minutes. Along with expansion into a whole new restaurant sector, the company has been expanding into the west coast. They recently announced a few new stores in Oregon and other parts of the west coast.


What has the stock done lately? 

To say the equity markets have had a shaky 2016 is an understatement. Since the start of 2016, the S&P 500 is flat, the Dow is up a measly 2%, and the Russell 2000 (where CBRL is listed) has come back from being down 15% to flat. In the same time period, CBRL is up 15%! With some analysts worried about a possible recession in 2016, a stock in the black is going to be hard to come about. In 2015, Cracker Barrel’s stock slipped 8%.


Past Year Performance: 2015 was a solid year for Cracker Barrel financially. Sales were up 6% from 2014, net income ripped up 25% in 2015, and net margins are currently increasing like they historically have—up 15%. As mentioned before, the stock depreciated 8% in 2015 and short interest is roughly 20%


Source: FactSet


My Takeaway 

I think Cracker Barrel could be one of the most promising, yet conservative, stocks for 2016. I view the stock as a win/neutral position. Lets say this fast casual concept takes off well and opens all sorts of new doors for the firm, then the company will see some serious revenue growth. Lets say the fast casual concept flops and they end of halting the project, then the company just relies on their historically successful business model. The company has the right management in place to keep the ball rolling and other institutional investors think so too. Institutions have gobbled up net 587,000 shares in the last month. I give Cracker Barrel to the latter half of 2016 before I consider buying more or selling my stake in the firm.