Sunday, July 27, 2014

CFA or MBA? Better Yet:How About the AIM Program?

In May 2013, Forbes ran an article: Should You Get A CFA, MBA Or Both? Much of the information below is from that article.

Additional education after college has become a prerequisite for career advancement in many investment fields. For those considering a career in investments, the great debate has been whether to obtain a Master of Business Administration or the CFA Institute’s Chartered Financial Analyst designation. Both have their advantages but considering the expense of the former and the difficulty of attaining the latter, choosing between the two makes for a rather difficult decision.

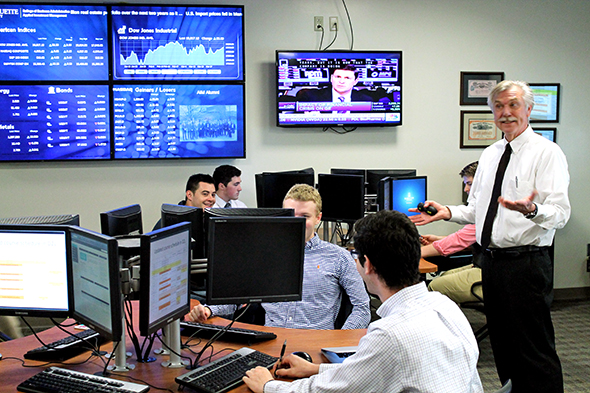
[Note: MarquetteUniversity’s Applied Investment Management (AIM) program in 2006 was named as the first undergraduate educational Program Partner of the CFA Institute. So for the students who have become members of the AIM program, they have had the opportunity to pursue the CFA designation immediately after graduating with their Bachelor of Science finance major].

To attract students, graduate institutions have begun to teach a large portion of the CFA program within the graduate business curriculum and some have gone as far as to create a “CFA track” within their MBA course of study, allowing students to obtain an MBA and a CFA at the same time. For those considering attaining both a graduate degree and the CFA certification, one of these programs is the most efficient way to get the best of both worlds.
[As previously noted, Marquette’s AIM program allows a select group of undergraduate finance majors to get hands-on academic and financial analysis experience, including an opportunity to actively manage domestic and international equity and fixed-income portfolios].

MBA vs. CFA?

Before the advent of the CFA, many investment companies would pay to send some of their best and brightest to business schools. These students would return with a much better general business skill, but not necessarily the skills needed for high-level, specialized asset-management responsibilities, such as portfolio management. These specialized skills were usually obtained on the job as professionals worked their way up through the ranks.

To generalize, the skills obtained in business school were better suited for employees in more general disciplines, such as marketing or general management. The CFA program was devised to provide charter holders with specialized skills, such as investment analysis, portfolio strategy and asset allocation. One way to explain the differences in the programs is to say that the MBA program is a mile wide and a foot deep, while the CFA program is a foot wide and a mile deep.

The advantage of an MBA is that the knowledge obtained in the program is valuable in other industries outside of the investment world. The great disadvantage is cost – both the direct cost of the program and the loss of income that results from a two-year hiatus for those considering going back to school full-time.

The advantages of the CFA program are the ability to acquire specific investment related skills at a relatively low cost. However, although the CFA program is based on self study, it is arduous, requiring a commitment of four years and 1,000 study hours (on average) to complete it. Because of the commitments both in time and money, few go on to acquire both the graduate degree and the certification.

The CFA Track

For many willing to make the commitment and meet the other prerequisites necessary to obtain a graduate business degree and the CFA, most will begin the CFA program right after graduation, hoping to use some of the knowledge gained in their finance courses to give them a leg up over other CFA candidates. However, until recently, most graduate business programs did not organize their finance curricula for this purpose, the advantage for graduates was minimal. This is changing, as business schools such as Marquette University have begun to incorporate CFA course work into their undergraduate offerings.

According to the CFA Institute, in July 2014 there were nearly 150 universities worldwide that are CFA Program Partners. These universities must provide at least 70% of CFA course work as part of their curriculum. The CFA Institute audits the course offerings of these partner institutions to ensure they live up to their promises. To attract students, undergraduate and graduate institutions have begun to teach a large portion of the CFA program within their graduate business curricula.

The curriculum offered by these program partner schools range from specialized finance courses aimed to facilitate the CFA exams, to a specific “CFA track,” which includes courses that teach the exam material. The CFA track usually is designed so that students will take Level I of the CFA exam directly after graduation.

The Bottom Line

Due to the program partnerships between business schools and the CFA Institute, there is now an efficient means for investment professionals to obtain both a graduate business degree and a CFA – or even to focus on CFA as an undergraduate. Whereas it used to be adequate to obtain one or the other, this trend and the number of new investment professionals acquiring both graduate degrees and the CFA may ultimately require professionals to obtain both. Where the commitment was once two years of graduate school and four years of self study, now candidates that choose a partnering institution can perform a majority of the CFA commitment within their graduate school course work. Although it will still require an immense amount of commitment and discipline, an increasing number of institutions allow investment professionals to gain both breadth and depth of knowledge for all the investment management disciplines. 

Or a student could opt to pursue a CFA track as an undergraduate at Marquette University within their Applied Investment Management program.


What About a Career as a Financial Analyst?


Rising juniors considering applying to Marquette’s AIM program should evaluate different career options. In the finance industry, one of the most desirable careers is that of being a financial analyst. In this article, we examine what financial analysts do.

The financial industry is highly competitive and it is challenging to break into the field, but it is possible to find a position as a financial analyst. After reading this article, if it seems like something you are interested in as a career, then maybe the AIM program is for you. Read on to find out more about a career as a financial analyst.

What Does a Financial Analyst Do?
A financial analyst researches economic, industry and company fundamentals to make business decision and investment recommendations. They often propose a course of future action, such as to buy or sell common stock based upon the firm’s current and forecasted strength. A financial analyst must be aware of current developments within the markets and industry trends. They must be capable of producing complex financial models in order to predict future economic conditions based on a wide number of variables.

Background of Financial Analysts
Since you might still be an undergraduate student who is considering a career as a financial analyst, it is best to take courses in finance, economics, accounting and mathematics. Other majors that are looked upon favorably include those in STEM (science, technology, engineering and math). Many of the entry level analysts hired by firms have these backgrounds, while MBA graduates are often hired as senior analysts right out of business school.

If you are not an MBA graduate student or an economics major as an undergraduate, you may want to consider studying for the Series 7 and Series 63 exams or participating in the Chartered Financial Analyst (CFA®) program. It is important to keep in mind that participating in these exams are challenging and will require sponsorship.

The CFA charter requires the passage of three annual exam that are highly technical; however, the Series 7 and 63 exams can be other ways for a student to prove a basic familiarity with investment terms and accounting practices. If you look at a sample CFA exam and it seems overwhelming, start with practicing for the Series 7 and 63 exams and then work your way up to the CFA exam or begin to interview for junior analyst positions after passing those Series exams. This is where being a member of the AIM program can help prepare you for the rigorous CFA exams.

Types of Analyst Positions
Financial analysts tend to specialize based on the type of institution they work for. Analysts are hired by banks, buy- and sell-side investment firms, insurance companies and investment banks. Of these specialties, three major categories of analysts are those that work for 'sell-side' investment firms, those that work for 'buy-side' investment firms and those that work for investment banks.

Within the investment industry, most analysts tend to work either for buy-side investment firms, where they research stocks for an in-house fund, or sell-side firms that write research reports for buy-side firms. Buy-side firms are investment houses that manage their own funds. In these companies, analysts research companies as they look for stocks to add to an investment fund. They also track the stocks that are in a fund's portfolio in order to determine when or if the fund's position in that stock should be sold.

At a sell-side firm, analysts evaluate and compare the quality of securities in a given sector or industry. Based on this analysis, the analysts then make reports with certain recommendations such as: buy, sell, strong buy, strong sell or hold. These recommendations carry a great deal of weight in the investment industry including analysts working within buy-side firms.

Even within these specialties, there are subspecialties such as analysts who specialize in equities and those that specialize in analyzing fixed-income instruments. Many analysts also specialize even further within a specific sector or industry. An analyst may specialize in energy or technology, for example.

Analysts in investment banking firms, however, differ from analysts in buy- and sell-side firms as they often play a role in determining whether or not certain deals are feasible based on the fundamentals of the companies involved in a deal. This type of analysis can include IPOs or mergers and acquisitions (M&A). Analysts assess current financial conditions as well as rely heavily on modeling and forecasting to make recommendations to senior partners as to whether or not a certain merger is appropriate for that investment bank's client or whether another client of the investment bank should invest private equity or venture capital in a particular company.

What to Expect on the Job
Financial analysts need to remain observant about gathering information on the overall economy as well as information about specific companies and the fundamental microeconomics of their balance sheets. In order to stay on top of financial news, analysts will need to do a lot of reading on their own time. Analysts tend to read publications such as The Wall Street Journal, The Financial Times and The Economist as well as financial websites.
Being an analyst also often tends to involve a significant amount of travel. Some analysts travel to companies to get a first-hand look at company operations on the ground level. Analysts also frequently attend conferences with colleagues who share the same specialty as they do.

When in the office, analysts learn to be proficient with spreadsheets, relational databases and statistical and graphics packages in order to develop recommendations for senior management and to develop detailed presentations and financial reports that include forecasting, cost benefit analysis, trending and results analysis. Analysts also interpret financial transactions and must verify documents for their compliance with government regulations.

Opportunities for Advancement
As interoffice protocol goes, analysts interact with each other as colleagues while they tend to report to a portfolio manager or other senior in management. A junior analyst may work his or her way up to a senior analyst in a period of three to five years. For senior analysts who continue to look for career advancement, there is the potential to become a portfolio manager, a partner in an investment bank or senior management in a retail bank or an insurance company. Some analysts go on to become investment advisors or financial consultants.

Tips for Success
The most successful junior analysts are ones that develop proficiency in the use of spreadsheets, databases, PowerPoint presentations and learn other software applications. Most successful senior analysts, however, are those who not only put in long hours, but also develop interpersonal relationships with superiors and mentor other junior analysts. Analysts that are promoted also learn to develop communication and people skills by crafting written and oral presentations that impress senior management.

The Bottom Line
While a career as a financial analyst requires preparation and hard work, it also has the potential to deliver not just financial rewards but the genuine satisfaction that comes from being an integral part of the business landscape.

.

Thursday, July 24, 2014

A message from Marquette's 24th president, Dr. Michael R. Lovell

Dear alumni, parents and friends:

It is a privilege to write to you as Marquette's 24th president. I'm humbled to be leading this wonderful university at such a historic time. Since my election by the Board of Trustees in March, I've been overwhelmed by the warm welcome I've received from alumni, parents, business leaders and members of the Milwaukee community. Through my initial experiences meeting our faculty, participating in Preview for members of the Class of 2017 and attending Mass at St. Joan of Arc Chapel, I already feel at home at Marquette. Since our Marquette family extends far beyond the boundaries of campus, I'm especially looking forward to getting to know you in my travels across the country during the coming year. From New York and Washington, D.C., to the Midwest and California, I'll be meeting Marquette alumni and friends across the nation. Please watch for additional information, and consider attending an event in your region.

As I assume the role of president, I want to express my sincere gratitude to Rev. Robert A. Wild, S.J., for his outstanding leadership during a remarkable 16-year tenure as Marquette's president. It's been a pleasure working with Father Wild during the transition as he helped bring me up to speed on the many opportunities and challenges facing our university. I look forward to continuing to work with him in his new role within University Advancement.

As we head into what is sure to be an exciting academic year, I'd like to highlight a number of initiatives that will be priorities on campus during the next several months. As a Catholic, Jesuit university committed to education that transforms students' lives, the leadership of our academic division is vitally important. To that end, the search for a permanent provost will resume in August. I look forward to meeting with the search committee, and I plan to work closely with them to identify a permanent provost, who will be Marquette's No. 2 leader. The search for permanent deans of the College of Business Administration and the College of Engineering will trail the provost search by about a month so that the permanent provost can be involved in the hiring of the deans.

Marquette has a proud history of academic and athletic excellence, and we need permanent leadership of our Department of Intercollegiate Athletics. The search for a vice president and director of athletics is already under way, with the hope that an individual will be in place this fall to lead our 16 Division I athletics programs to success both on and off the field.

In addition to these leadership searches, I look forward to working with senior leaders, faculty, staff, students and the broader campus community to implement our strategic plan and to renew our commitment to innovation across campus. Working together, we will begin to prioritize initiatives that fulfill our vision of being recognized among the most innovative and accomplished Catholic, Jesuit universities in the world. One of my central priorities is to enhance an already-strong student experience and tradition of inquiry and service, which have allowed Marquette to make a profound impact on the lives of others for more than 130 years.

Finally, I invite you to join me for Inauguration events this fall, particularly the Inaugural Mass on September 18 and the Inauguration Ceremony on September 19, at which I will pledge my service to Marquette. I look forward to doing so in the presence of our Marquette community on campus and our more than 110,000 alumni around the world, who can watch the Inauguration Ceremony via a live webcast on the Inauguration website. 

And for those coming home to Marquette for Alumni Reunion Weekend, July 24–27, I encourage you to introduce yourself. I will be attending events throughout the weekend and look forward to hearing about your Marquette memories and experiences.

As I take on this new role, I'm indebted to the great Jesuit leaders who came before me and the spirit of discovery that infused their dreams for this fine institution. I want to ask you all, whatever your faith may be, to pray for me that God may give me wisdom and strength to carry out my duties and that I may faithfully serve God and Marquette.

Sincerely,

Michael R. Lovell
President
Marquette University

Marquette be the DifferenceMARQUETTE UNIVERSITY. Be The Difference.
P.O. Box 1881 .
Milwaukee, WI 53201-1881

How to Break Into Finance & Banking


Have you always been interested in accounting, finance, and investing? Have you ever wondered what it might be like to work on Wall Street? These three young professionals felt the same way, and they went for it. But while they all started out after college as investment bankers, their careers now look very different from one another.


As rising juniors prepare to apply to the AIM program at Marquette University, they should be giving serious consideration to their career choices. This article, "How to Break Into Finance & Banking" is from  The Daily Muse, April 2013.


Read on to hear their stories and see where a career in finance might lead you, plus get some insider tips for breaking into the industry. To those Marquette students who have attended the annual "Ins and Outs of Wall Street" during the spring semester, they understand more about the career options available. Nevertheless, this article offers some interesting perspectives.

Jennifer Bennett - Financial Advisor, Morgan Stanley
Brief Description of Job: Wealth management for high net worth individuals and families.
Years of Industry Experience: 10

Why did you choose this field?
I was attracted to the opportunity to work closely with clients and learn about their financial lives. I always had a general interest in personal finance and investing, but it was the chance to work not just as an investment advisor but also as a financial counselor that really intrigued me.

I enjoy getting to know my clients: what they find important, what they want to achieve in life, and where they see themselves in the future. So much of this job is about listening. If you don’t genuinely have an interest in and care about your client’s financial well-being, then they can see right through you.

What did you want to do in college?
I wanted to work on Wall Street, and when I landed a job at an investment bank after college, I thought I had made it. While it was a great learning experience to work on the institutional side of the business as an equity analyst, I came to realize that it wasn’t what I wanted to do longer term. I wanted to have a more personal connection with my clients. I’ve always been a planner and interested in investing, so the financial advisor role was a natural fit for me. 

What advice would you have for someone breaking into your field?
It’s a great profession, but not always an easy ride to get there. Turnover for new entrants is brutally high. If you’re motivated to beat the odds, plan on spending a lot of late nights and weekends at the office to make it happen.

In the early years, most of your time is spent trying to grow your client base—in fact, finding clients is crucial to your success. Whether you find them by giving seminars or presentations, through social or business contacts, or at networking events, find them you must. This is a tough business, but it can be very rewarding for those who can distinguish themselves. Once you can demonstrate that you provide value, more and more of your new clients will come as referrals from existing ones.

What has been the most surprising thing about working your field?
I find it surprising the relationship that people have with money: how they spend it, how they save it, and what it means to them. Money can’t buy happiness, but it sure can bring peace of mind. It can also bring stress and conflict.

There are an abundance of investment options on the market and the wealth planning process can be confusing. Most clients that I work with don’t have the desire to understand what the beta or standard deviation is on their portfolio—they just want to know that they are saving and investing appropriately to accomplish their goals. Sometimes clients set goals that are unrealistic, and so then it becomes a matter of breaking down each goal into manageable areas.

What I enjoy most about my job is trying to demystify the world of finance and helping clients make smarter financial decisions.


Steve Chien - Investment Banker, BNP Paribas
Brief Description of Job: Mergers and acquisitions advisory
Years of Industry Experience: 4

Why did you choose this field?
Investment banking provides a steep learning curve, friendly camaraderie with other college grads, and a wide range of exit opportunities. Former colleagues of mine have moved onto hedge fund investing, grad school, startups, or strategy and business development in a variety of industries.

It’s also one of the few ways for a recent graduate to afford to live in NYC. One of the best aspects of the day-to-day work is that I don’t just provide clients advice on transactions and strategy, but I also get to participate in the execution, unlike many types of consulting.

What did you want to do growing up?
Be a spy like James Bond.

What has been the most surprising thing about working your field?
Networking with recruiters and headhunters can be as helpful as networking with family and friends. Many smaller financial services firms, including hedge funds and private equity investment companies, are lightly staffed with respect to HR, and they rely on recruiters to be gatekeepers.

What advice would you have for someone breaking into your field?
Some junior banker candidates I’ve interviewed focus solely on their technical skills, such as accounting and finance jargon, in interviews. While technical skills are an important element of a junior banker’s skillset, it's just as important to be a human being and to not take yourself too seriously. Every interviewer will be trying to answer the question, “Will this person be tolerable—or better yet, make my life better—when we're working late?”

What is different about the hiring process in your field than in other fields?
Cover letters are rarely read, so I wouldn’t recommend spending much time crafting them. Smaller firms may take them into consideration, but a typical bank hiring process will filter through hundreds or thousands of resumes, and generally anything more than a brief and friendly note introducing yourself and directing the reader to the attached resume is unlikely to make a difference.

What industry-specific job search resources would you recommend?
Mergers and Inquisitions provides career and interviewing advice for the investment banking and investment management industries, and Wall Street Oasis hosts discussion boards frequented by junior finance types.


Ashley Harris - Corporate Development Associate
Brief Description of Job: Corporate development, business development, M&A, capital raising, and financial analysis
Years of Industry Experience: Going on 4

Why did you choose this field?
I started my career at a bulge bracket investment bank on Wall Street; I was told it was a useful starting point for future business leaders and thought, “Hey, why not—can’t be that bad.”

Having been a history and business psychology double major at a liberal arts-focused university, I found that finance was certainly an acquired taste that I eventually got the hang of over time. However, I’m a people person and a right brain, and I saw years of Excel models, PowerPoint pitches, and sleep deprivation in my future. As my two-year analyst program came to a close, instead of searching for private equity or hedge fund opportunities, I opted for corporate development.

My interest in corporate development initially stemmed from my desire to get closer to the fundamentals of how a company is run. As an investment banking analyst, the numbers on my screen were meaningless. As a corporate development associate at an early-stage venture, it is my job to look at those numbers and say, “Who, what, when, where, why, and how?” on a daily basis.

What has been the most surprising thing about working your field?
My corporate development experience has been characterized by the fact that I’m able to touch every facet of what we do. I started at the ParentCo, stayed on for a year, then participated in the initial organizational strategy and capital raising for the company where I now work, which is structured as a joint venture between the ParentCo and a private equity firm far away from Denver, our home base.

Many times you hear corporate development and you think, “M&A and capital raising,” but for a company, not an investment bank representing a company. Usually, in a company’s lifecycle, M&A and capital raising fall somewhere in the middle, after the company has established itself in its market. At my company, M&A and capital raising were our very first steps, and only now are we in market establishment mode. ParentCo and Private Equity Firm joined together and funded an idea (not assets, which would have been slightly more normal) in October 2012, and I’m lucky enough to have become a part of the team that makes that idea come to fruition.

That said, I do everything at our company, from business development to board-level reporting and participation to marketing and advertising to miscellaneous and non-glamorous roles like creating invoices, IT, and generating efficient systems that get everyone organized. Down the road, I’ll do more M&A and capital raising-centric work, but we have to be successful in our business development first.

In my opinion, the best thing about being a corporate development professional is that you are able and have the tools necessary to look at an organization and say, “Where can I help?” While I certainly wasn’t in my professional prime as an investment banking analyst, it definitely provided me with some of the tools I needed to ask that question.

What advice would you have for someone breaking into your field?
Networking is absolutely key. That’s important to remember, because investment banking analysts are very accustomed to having recruiters come to them, but companies looking for corporate development professionals aren’t necessarily going to use recruiters for their searches. The process can get very competitive, especially in New York, but it’s generally successful—everyone from my banking class was able to secure a role somewhere after our term ended.

My best advice to someone looking for a role in corporate development is to pick an industry and meet as many people as you can in that industry, and more often than not, an interesting role requiring a finance background will pop up. And even if it’s a “miscellaneous finance” role, my favorite part of my past two-ish years at my company has been my ability and my supervisor’s willingness to transform my role into something I’m really confident in. That might be unique to the early-stage role, but I truly believe that if you prove you’re valuable to a company, you can make yourself fit wherever you’re looking to fit (and wherever you’re most confident!).

Moreover, I moved to a “non-target” city, Denver, and very much took a leap of faith. I knew literally no one and I moved for an industry I hoped I would be passionate about (unconventional oil and gas development). But about a year and a half later, taking that chance was the best thing I could have done for myself and my career, and I can only hope it continues to pay dividends. Flexibility, willingness to be mobile, and an open mind are essential.

Wednesday, July 23, 2014

Dr. Krause comments on local OTC stock seeking to jump to NASDAQ

Cellectar, an OTC Stock, Eyes Nasdaq Jump to Boost Profile, Prospects

7/22/14Follow @XconomyWI
Cellectar Biosciences is trying to move from an over-the-counter (OTC) stock to trading on the Nasdaq stock exchange—and the stakes are high for the small Madison, WI-based biotech.

Winning approval to join the Nasdaq stock exchange could give Cellectar a boost in bringing its cancer drugs and imaging products to market—assuming the company can capitalize on the opportunity. And at the very least, Cellectar would raise its profile in both the investment and research communities by moving into the big leagues of a major exchange.

Whether it’s fair or not, small companies whose stock trades OTC often are associated with penny stocks—a “pejorative term,” says Eric Blanchard, a partner with law firm Covington & Burling in New York. As “The Wolf of Wall Street,” last year’s raucous Martin Scorsese flick, vividly describes, penny stocks can be manipulated in fraudulent “pump-and-dump” schemes.

But many OTC stocks can’t be tarred with the same brush as dubious penny stocks, adds Blanchard. (The SEC defines penny stock as securities issued by small firms that trade at less than $5 per share, generally OTC. Others set the threshold at $3 or $1 per share.) Indeed, for many small private companies, which don’t have enough visibility for a splashy IPO on a major exchange, trading their stock OTC is a logical next step for raising capital after the family and friends stage, despite the negative perception, says David Krause, a Marquette University finance professor and director of the Milwaukee school’s Applied Investment Management program. “Not every stock is Google or Apple; they have to start out oftentimes raising money where they can, and it may be in the penny market,” he explains.

Biotech and software startups sometimes go the OTC route because they lack the tangible assets, like industrial manufacturing equipment, that can be used as collateral to more easily obtain financing, he says. Or they can end up as an OTC stock as the result of a merger, as in the case of Cellectar. The once privately-held company was acquired in 2011 by Newton, MA-based Novelos Therapeutics, which was already an OTC stock, and which moved the headquarters of the combined company to Madison, where Cellectar was based.

It’s not the preferred path, Krause says. “Firms would try to avoid it if they could because of the connotation.” He equated it to hawking wares at a pawnshop. “It doesn’t mean you’re a bad person and that the money you’re raising isn’t valid, it’s just not the normal route that people—or in this case, businesses—go to raise money.”

That’s why some ambitious executives view trading OTC as a way station on the path to better things. Making the jump to a major stock exchange opens the business up to more liquidity and a bigger pool of investors, says Matt Rossiter, a corporate partner with Fenwick & West in San Francisco. And given investors’ recently revived interest in biotech companies (although the biotech IPO market might be cooling), now might be a good time for the sector’s startups to try to “up-list” from trading OTC to the Nasdaq—the home of most small, publicly traded biotechs. “It helps because investors are more aware of the sector and more optimistic about its prospects,” Rossiter says.

Cellectar’s executives and investors hope he’s right. The company recently enacted a 1-for-20 reverse stock split and announced it had applied to trade on the Nasdaq Capital Market, while also planning a public offering of additional shares. The firm awaits approval by the Nasdaq, which depends on a set of criteria that include having a bid price of at least $4 per share, at least 300 shareholders, and at least 1 million publicly held shares, among other requirements. A Cellectar spokeswoman declined to comment, citing a company quiet period while the Nasdaq considers its application. But in mid-July, the company’s stock was trading above $6 per share, and its investors held 2.87 million shares.

The company has disclosed plans to trade on the Nasdaq at least once before,back in July 2011, three months after Novelos acquired it. But the company pulled back until now, when its stock price is higher and the R&D pipeline looks stronger.

“My personal opinion is I’m quite confident that we will succeed this time,” says Wisconsin businessman Jeff Straubel, an early investor in Cellectar. “It has most to do with the fact that I think we are gaining a good deal of acceptance with the right community,” namely scientists. Straubel cited recent buzz among researchers after Cellectar published a study in Science Translational Medicine that showed its compounds were effective in imaging and treating human tumors that had been surgically grafted into mice, and in detecting tumors in a small group of human patients—although a co-author of the study told The Scientist that more clinical work will be required to “optimize the imaging and therapy parameters.”

But the potential of Cellectar’s science won’t affect the outcome of its Nasdaq application, which will likely be decided upon in the next 60 days or so, Marquette University’s Krause estimates. The decision will have a huge impact on the company’s future. Cellectar’s ability to raise additional financing to develop its cancer drugs and imaging agents likely hinges on making it on the Nasdaq exchange, says investor Straubel. Straubel is president and majority owner of Wisconsin-based Greenway Properties, which currently holds nearly 22 percent of Cellectar’s shares, SEC filings show. “These sophisticated, larger biotech investors, especially, only deal with companies which are traded [on a major exchange] and have a good deal of liquidity,” Straubel says. “They just don’t take a company as serious which has a very low liquidity and a very low stock price.”

Cellectar was founded in 2002 by UW-Madison radiology professor Jamey Weichert, who currently serves as chief scientific officer. The company raised more than $23 million in venture capital between 2002 and 2010 to develop compounds from Weichert’s lab called phospholipid ethers (PLEs). Researchers have known for several decades that these PLEs have an unusual and potentially valuable property: The PLEs become trapped inside malignant tumor cells because cancer cells apparently don’t have the ability to metabolize and eliminate the molecules. As a result, PLEs could be used as a vehicle for fluorescent or radioactive material that would help detect and map the locations of cancer cells, or to deliver drugs or sources of radiation to the cancer cells. Such targeted drugs should theoretically cause far less damage to healthy cells than typical cancer drugs do, thus minimizing side effects. Cellectar has created three novel cancer-targeting products that utilize PLEs: one therapeutic compound and two imaging agents that are at various stages of development, from pre-clinical to a Phase II trial.

The product pipeline showed enough promise for Novelos to snatch up Cellectar in 2011, a year after Novelos’ leading cancer drug candidate failed a Phase III trial. Novelos moved to Madison to continue developing Cellectar’s products. The combined company renamed itself Cellectar Biosciences (OTCQX: CLRB) this year and raised $4 million in a private placement offering of convertible debt. The new money will help fund a Phase II trial of its positron emission tomography (PET) imaging compound in glioblastoma, a type of brain or spinal tumor.

If Cellectar does win Nasdaq approval, it won’t be the only small biotech that successfully graduated from the OTC market to a bigger exchange. San Diego-based Halozyme Therapeutics, for example, went from privately held to trading OTC in 2004 when it completed a reverse merger with Global Yacht Services. It later traded on the American Stock Exchange (now the small-cap NYSE MKT), beforejoining the Nasdaq in 2007.
More recently, New York-based Retrophin did a reverse merger in 2012 withshell corporation Desert Gateway, which was traded OTC. Retrophin startedtrading on the Nasdaq in January.

Small OTC biotechs considering a move to a bigger exchange can draw a couple lessons from Retrophin’s strategy, says Blanchard of Covington & Burling. His law firm represented the underwriters in Retrophin’s $40 million public offering, which occurred simultaneously with its application to trade on the Nasdaq Global Market. Conducting a public offering of at least $40 million in tandem with the application provides a fast track to the Nasdaq, Blanchard says.
Another part of the secret to Retrophin’s success, Blanchard says, was a pair of private placement offerings totaling $35 million, which were completed in the months leading up to its Nasdaq IPO. “They sought out some large investors who were really interested in the story,” Blanchard says. “They basically established a devoted shareholder base even before they did their up-listing, which is actually a good way to do it. Then once they did the up-listing, their stock shot straight up.”

Retrophin (NASDAQ: RTRX) priced the $40 million offering at $8.50 per share. It went on to trade as high as $25 per share, Blanchard says. It closed at $10.23 per share on Monday.
So will Cellectar make it to Nasdaq? Although Blanchard didn’t want to comment directly on Cellectar’s prospects, he did say that it appears the company is taking the appropriate steps to win Nasdaq approval. It’s conducting a public offering alongside the Nasdaq application, for instance, and it has already boosted its share price with the 1-for-20 reverse stock split. The latter is especially important because the biggest hurdle to listing on the exchange is typically a company’s stock price, Blanchard says. The higher the better. Cellectar closed at $6.50 per share on Monday.

Besides gaining access to a larger pool of investors, the rewards for making it onto a bigger exchange include increased buzz around the company and a big boost in its credibility, industry observers say.

But it’s not all positive. The flipside is more scrutiny. “When you open up investment to a broader array of people, not just VCs, it’s actually in some ways a bit more stringent because you’ve got more people with more ideas looking at it,” says Les Funtleyder, a former biotech financial analyst who is now a New York-based partner with international healthcare investment advisor BlueCloud Healthcare. “But it does add a certain legitimacy to your company. But I say that with an asterisk because the reality is if the IPO is weak, then as a management team, you have to overcome that. That will raise questions in other public investors’ minds, which can be dealt with if you put up good results.”

Rossiter agreed that moving to the Nasdaq only opens the door to more financing and visibility. Then it’s time to execute.

“The challenge is this is just a step on the journey toward building a company and also financing a company,” Rossiter says. “The challenge is to capitalize on that in some way.”
Jeff Engel is the editor of Xconomy Wisconsin. Email: jengel@xconomy.com

Tuesday, July 22, 2014

The CFA Institute released the 11th edition of the Standards of Practice Handbook (effective 1 July 2014)

Marquette's AIM program has been a CFA Program University Partner since 2006. Students in the program aspire to become a CFA charterholder.

The principles and guidance presented in the CFA Institute's Standards of Practice Handbook form the basis for the CFA's self-regulatory program that seeks to maintain the highest professional standards among investment practitioners. A clear understanding of the CFA Institute Code of Ethics and Standards of Professional Conduct (both found in the Handbook) should allow the practitioner to identify and appropriately resolve ethical conflicts.

The eleventh edition of the Standards of Practice Handbook contains the CFA Institute Code of Ethics and Standards of Professional Conduct with related guidance and examples illustrating application of the Standards in the day-to-day professional activities of members and candidates. The eleventh edition guidance and provisions are effective 1 July 2014 and can be downloaded for free at:  http://www.cfapubs.org/toc/ccb/2014/2014/4.